
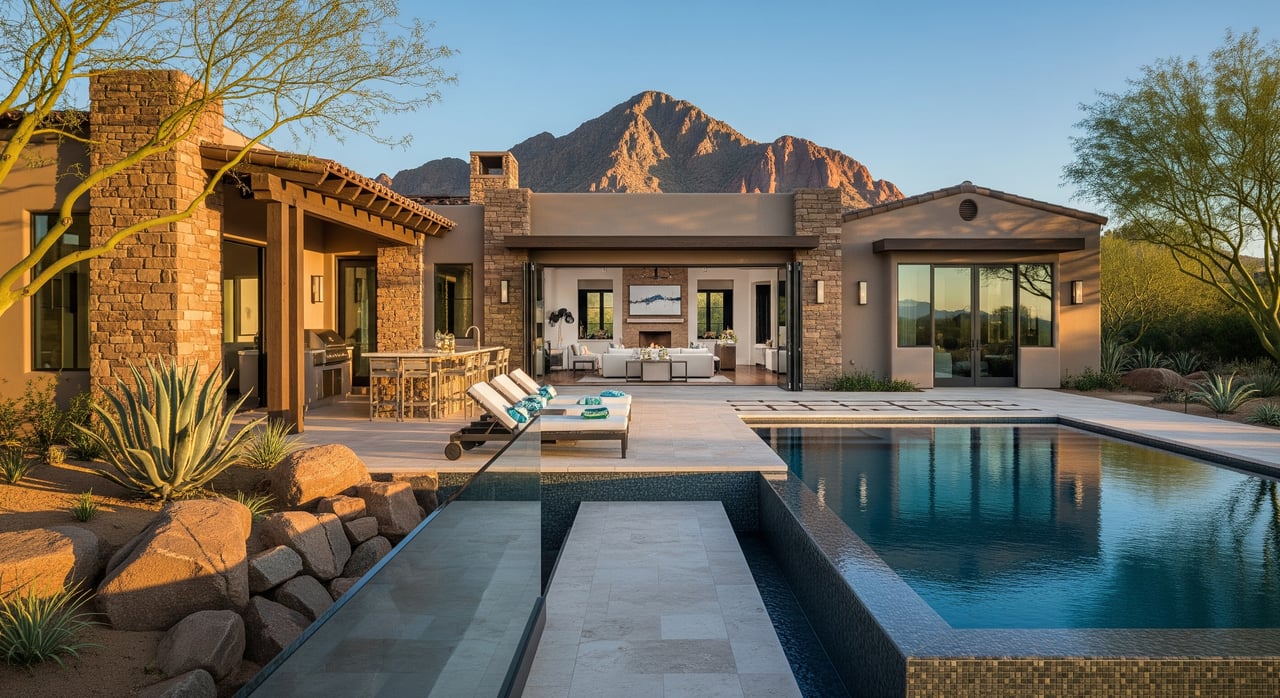
Buying or selling a Paradise Valley home with a breathtaking view or bespoke design? The appraisal can be the turning point that keeps your deal on track or slows it down. You want clarity on how value is determined when every property is custom and true comparables are scarce. In this guide, you’ll learn how appraisals work for luxury homes in Paradise Valley, how appraisers handle views and unique features, and what you can do to prepare and respond if the value comes in low. Let’s dive in.
What an appraisal is and isn’t
An appraisal is an independent opinion of market value prepared as of a specific date. Lenders use it to underwrite your loan, and appraisers follow USPAP standards along with lender rules. It is not a guarantee of the contract price or a home inspection.
Appraisers can use three approaches to value, applying what fits best:
- Sales Comparison: Compares your home to recent closed sales, then adjusts for differences like view, lot, size, and condition. This is the primary method for most residential properties.
- Cost Approach: Estimates land value plus the cost to rebuild improvements, minus depreciation. It is most relevant for newer custom homes or when sales data is limited.
- Income Approach: Used when a property produces income. Most owner-occupied luxury homes in Paradise Valley will not rely on this approach.
Why Paradise Valley appraisals are different
Paradise Valley is a small, luxury market with many custom homes on large lots. Properties often feature mountain or city views and one-of-a-kind materials and layouts. That uniqueness creates a wide range of values and longer marketing timelines compared with more uniform neighborhoods.
Inventory is thin and some sales are private or off-market. This limits the pool of comparable sales, so appraisers may need to look at older closings, adjust more heavily, or consider nearby communities when justified. The result is a valuation process that demands strong documentation and local expertise.
How appraisers value custom and view homes
Sales comparison in thin markets
The sales comparison approach remains the backbone of luxury appraisals. In Paradise Valley, the challenge is finding sales that match your home’s view quality, lot size, floor plan, and finish level. When ideal comps are scarce, appraisers may consider older sales or those farther away, then apply thoughtful adjustments to bridge the differences.
Adjustments must be supported by market evidence. That can include paired sales, interviews with market participants, and verifiable data from closed transactions. The more credible evidence you provide, the more defensible the final opinion of value becomes.
Cost approach as a reality check
For newer or extensively rebuilt custom homes, the cost approach can help. Appraisers estimate land value separately, then add the cost to reproduce or replace the improvements, minus depreciation. In Paradise Valley, where land value is often a major factor, this approach can serve as a useful cross-check alongside recent sales.
View and lot premiums
View quality is treated as a measurable attribute when there is support. Appraisers look for sales of similar homes with and without comparable views to quantify a premium. If no direct paired sales exist in the immediate area, they may seek broader regional indicators, which can invite more scrutiny from lenders.
Lot characteristics matter, too. Topography, orientation, privacy, and site work all impact value. Clear photos and site plans help appraisers understand what a buyer is paying for beyond the walls.
What rarely applies: income approach
The income approach is typically reserved for properties that produce income. For most owner-occupied luxury homes in Paradise Valley, this method is not central to the final value.
Common appraisal challenges here
- Limited and imperfect comps: Smaller market size and off-market closings reduce available sales. Appraisers may rely on older closings or nearby communities, then apply larger adjustments.
- High variability in features: Finishes, floor plans, casitas, pools, automation, and landscaping vary widely. Each feature needs support for any adjustment.
- Renovation vs. new construction: High-end remodels add value when backed by permits, invoices, and clear market acceptance. Limited documentation reduces the weight given to claimed upgrades.
- Off-market and non-arm’s-length sales: Private financing or relationship-based deals can distort signals. Appraisers will note, adjust, or exclude these sales as needed.
- Market segmentation: Luxury buyers behave differently than mainstream buyers. Seasonality and interest rates can affect demand, time on market, and perceived value.
How you can help support value
You can make the appraiser’s job easier and protect your outcome with thorough documentation. Share it early and organize it clearly.
Provide an evidence packet with:
- A shortlist of recent, relevant sales from the past 6–12 months, including MLS sheets and settlement statements when available.
- An itemized list of upgrades and costs, with permits and contractor invoices for major work.
- Professional photos highlighting premium finishes, outdoor living, and all view corridors from main living areas and the primary suite.
- A floor plan with gross living area noted and the measurement method documented.
- A survey or site plan, plus lot photos showing topography, privacy, and access.
- Evidence of land value, like recent land-only or adjacent lot sales.
- Documentation of rental potential if the property is marketed as an investment.
Pre-listing valuation options
- Full appraisal by a local appraiser experienced with Paradise Valley luxury homes. This can surface risks early and reduce surprises.
- A broker price opinion or CMA provides guidance but does not replace a lender-required appraisal.
Using comps when inventory is thin
When the comp pool is small, context is everything. Encourage collaborative, compliant communication with the lender and appraiser. Provide your best comps with backup documents, explain why they are relevant, and describe any sales that should be excluded due to unusual terms.
Smart questions to ask the appraiser or lender:
- “Do you have experience valuing Paradise Valley custom homes and view properties?”
- “What comps do you plan to use, and will you consider off-market sales if I provide documentation?”
- “How will you quantify view and lot premiums here, and what evidence would you find most persuasive?”
- “Would a pre-listing appraisal and additional documentation make the report more defensible?”
What to do if value comes in low
An appraisal gap happens when the appraised value is below the contract price. You still have options. Decide which strategies fit your goals, timeline, and financing before you enter escrow.
Seller options
- Price reduction: Simple and fast, though it lowers proceeds.
- Seller credit at closing: Offsets buyer costs within lender limits.
- Escrow holdback or short-term seller carryback: Seller finances part of the difference for a short period. This requires proper documentation and lender approval.
- Pull back certain inclusions: Removing furniture or seller-paid items can alter the price and net.
Buyer and financing options
- Increase down payment: Cover the gap so loan-to-value is based on the appraised amount.
- Bridge or private funds: Temporarily cover the shortfall while terms are revised or a new appraisal is obtained.
- Different loan program: Some jumbo or portfolio lenders may have more flexibility. Cash buyers do not require an appraisal for lender purposes.
- Appraisal waiver: Rare for luxury homes but possible depending on program and underwriting.
Transaction-level tactics
- Reconsideration of Value: Submit a formal packet with stronger comps, upgrade documentation, land evidence, and view photos. Lenders typically allow one ROV.
- Second appraisal: Often allowed, though policies vary. The lender may accept it or require a reconciliation by another appraiser.
- Credible off-market evidence: Provide signed settlement statements and listing materials for private sales to support value.
- Appraisal contingency language: For sellers, clarify dispute processes and provide a list of relevant comps. For buyers, ensure your contingency protects you if you cannot increase funds.
Lender limits to confirm
Conventional and many jumbo lenders have specific rules for concessions, holdbacks, and seller-financed seconds. Confirm what your program allows before you structure a solution. Your agent and lender can help you stay within guidelines.
Best practices for smooth closings
- Hire local expertise: Choose professionals familiar with Paradise Valley view premiums and land valuation.
- Prepare a strong file: Share permits, invoices, photos, floor plans, and comp packets early.
- Align expectations: Consider a pre-listing appraisal for unique or highly customized homes.
- Plan ahead: Decide which gap-bridging strategies you are comfortable with before you accept or write an offer.
- Communicate clearly: Keep the appraiser and lender informed within allowed channels for a smoother process.
Get local guidance
In a market of custom builds, dramatic views, and limited comps, the right preparation can protect your price and timeline. If you are selling, an early documentation strategy can reduce risk. If you are buying, clear financing plans and a backup path can keep your deal moving even if the appraisal surprises you.
Have questions about your property’s value or next steps? Connect with Jennifer Taege for neighborhood-specific guidance and a plan tailored to your goals.
FAQs
How do luxury appraisals work in Paradise Valley?
- Appraisers rely on the sales comparison approach, supported by the cost approach when helpful, while carefully adjusting for view, lot, size, and finish differences.
How do appraisers value mountain or city views?
- They look for paired sales or similar homes with and without comparable views to support a measurable view premium, then document the evidence used.
What happens when there are few comparable sales?
- Appraisers may use older sales, consider nearby markets when justified, and apply larger adjustments, all supported by credible documentation.
How can I reduce the risk of a low appraisal before listing?
- Order a pre-listing appraisal, gather permits and invoices, prepare a detailed upgrade list, compile strong comps, and provide land and view documentation.
Can I challenge a low appraisal as a buyer or seller?
- You can request a Reconsideration of Value with better comps and documentation, or pursue a second appraisal if allowed by the lender.
Do cash buyers need an appraisal in the Paradise Valley luxury market?
- Cash buyers are not required to obtain a lender appraisal, though some still order one for an independent opinion of value.